
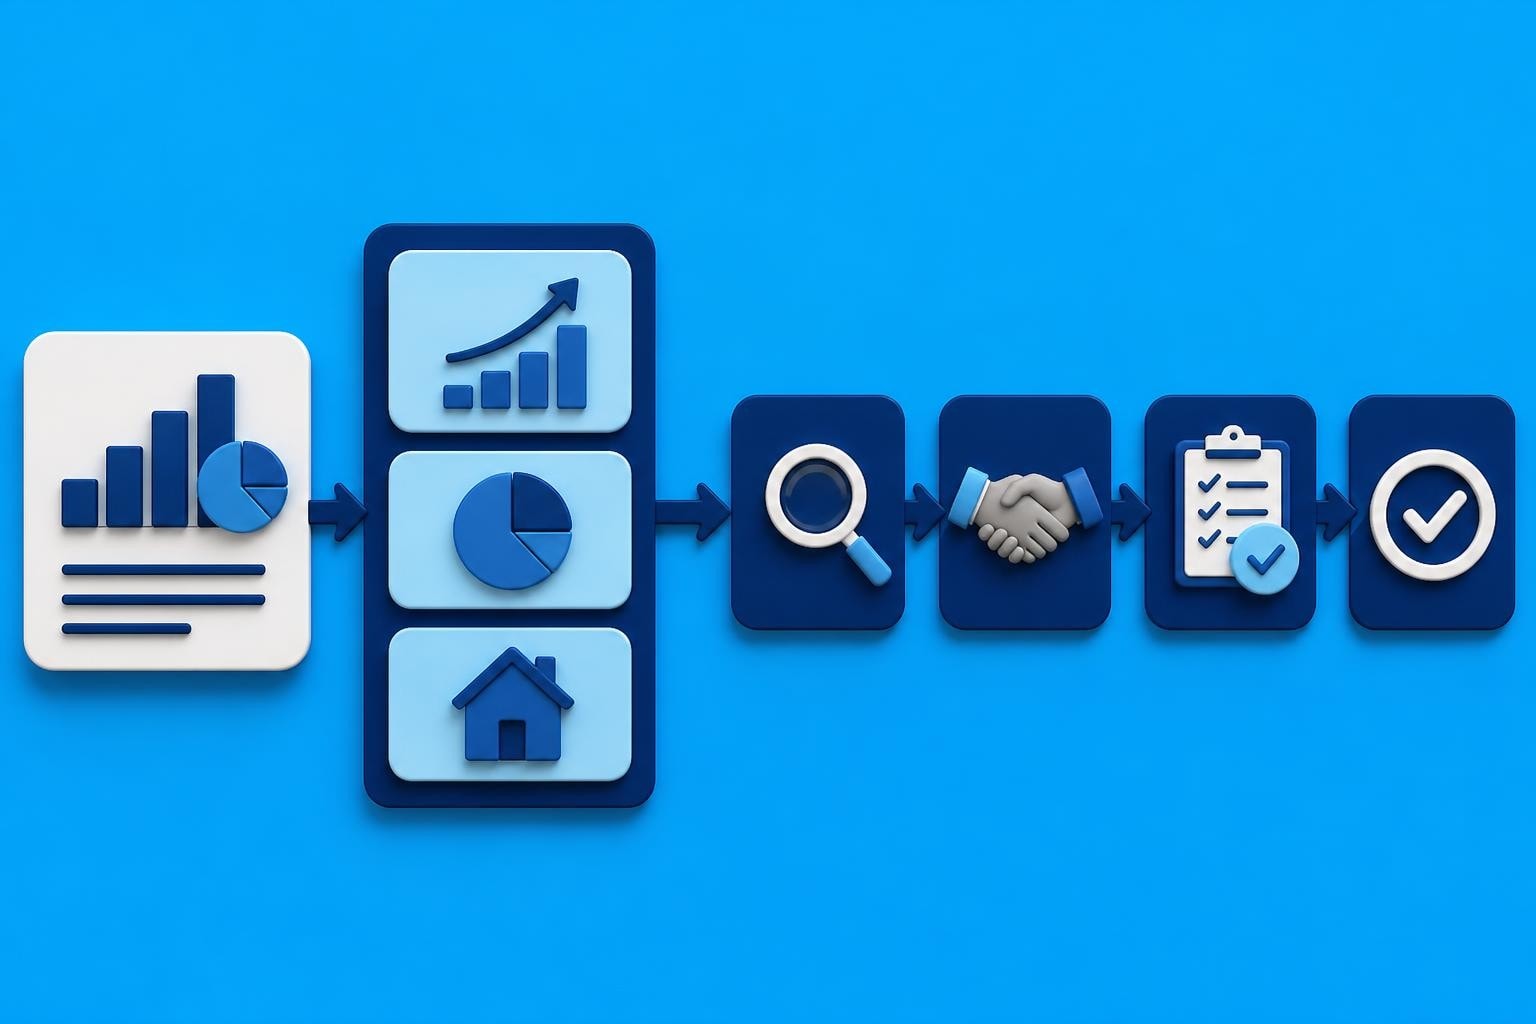
Understanding the true worth of a business represents one of the most critical challenges in mergers and acquisitions. Whether you're a potential buyer evaluating an acquisition target, a business owner preparing for an eventual exit, or an M&A advisor guiding clients through transactions, calculating business valuation requires a methodical approach grounded in both financial rigor and market realities. The valuation process serves as the foundation for negotiation, deal structuring, and ultimately determining whether a transaction makes strategic and financial sense for all parties involved.
Core Valuation Methodologies for M&A Transactions
When calculating business valuation, professionals typically employ three primary approaches, each offering distinct perspectives on company worth. The income approach focuses on future cash flow generation, the market approach compares the business to similar transactions, and the asset-based approach examines the underlying value of company resources.
Income-Based Valuation Methods
The Discounted Cash Flow (DCF) method stands as the most theoretically sound approach to calculating business valuation. This methodology projects future free cash flows and discounts them to present value using a weighted average cost of capital (WACC) or other appropriate discount rate. The comprehensive overview of valuation methods demonstrates how DCF analysis captures both operational performance and the time value of money.
Key components of DCF analysis include:
- Projected revenue growth based on historical performance and market conditions
- Operating margin assumptions reflecting competitive positioning
- Capital expenditure requirements for maintaining and growing operations
- Working capital changes as the business scales
- Terminal value calculation for cash flows beyond the projection period
- Discount rate selection incorporating risk factors and capital structure
For lower middle-market transactions, calculating business valuation through DCF requires careful attention to projection reliability. Smaller businesses often exhibit greater volatility in cash flows, making conservative assumptions essential for credible valuations.
| DCF Component | Typical Range | Key Considerations |
|---|---|---|
| Projection Period | 5-10 years | Industry stability, management visibility |
| Discount Rate | 12-25% | Size premium, industry risk, capital structure |
| Terminal Growth | 2-4% | GDP growth, industry maturity |
| EBITDA Margins | Industry-specific | Historical trends, competitive dynamics |
The Capitalization of Earnings method provides a simplified alternative for stable, mature businesses. This approach divides normalized earnings (typically EBITDA or seller's discretionary earnings) by a capitalization rate, effectively assuming perpetual cash flows with modest growth.
Market-Based Valuation Approaches
Market multiples offer a practical, market-tested approach to calculating business valuation. By examining recent transactions of comparable companies, buyers and sellers can establish valuation benchmarks grounded in actual deal activity rather than theoretical projections.
Common valuation multiples include:
- Enterprise Value to EBITDA (EV/EBITDA)
- Price to Earnings (P/E) ratio
- Revenue multiples for high-growth or pre-profitable businesses
- Industry-specific metrics (subscribers, units, locations)
When valuing a company using market multiples, selecting truly comparable transactions proves challenging. Size matters significantly-lower middle-market PE firms typically pay different multiples than strategic acquirers or larger private equity funds. Geographic location, growth trajectory, customer concentration, and competitive positioning all influence appropriate multiple selection.
The precedent transaction analysis examines actual M&A deals involving similar businesses. This methodology provides real-world validation of valuation ranges but requires careful adjustment for deal-specific factors like synergies, transaction structure, and market timing.
For businesses exploring strategic exits through platforms focused on matching buyers and sellers based on fit rather than just price, understanding how different buyer types approach calculating business valuation helps owners prepare more effectively.
Financial Statement Adjustments and Normalization
Accurate valuation demands properly normalized financial statements that reflect the true economic earnings power of a business. Many privately held companies include discretionary expenses, non-recurring items, or owner-specific costs that distort actual performance.
Common Normalization Adjustments
Owner compensation frequently exceeds market rates in private companies. Calculating business valuation requires adjusting owner salaries, bonuses, and benefits to reflect what a professional manager would command. Similarly, family members on payroll may receive above-market compensation that should be normalized.
Non-recurring expenses like litigation settlements, one-time professional fees, or facility relocation costs must be identified and excluded. Conversely, deferred maintenance or underinvestment in areas like technology or marketing may require downward adjustments to reflect true sustainable earnings.
Personal expenses run through the business-from luxury vehicles to travel unrelated to business development-should be added back to earnings. The US Chamber practical guide to calculating business valuation emphasizes these adjustments for small and medium-sized businesses.
| Adjustment Category | Typical Impact | Documentation Required |
|---|---|---|
| Owner Compensation | +$50K-$500K | Comparable salary data, organizational chart |
| Personal Expenses | +$20K-$200K | Detailed expense review, vehicle records |
| Non-recurring Items | +/- varies | Legal settlements, facility costs, one-time projects |
| Deferred CapEx | -$30K-$300K | Equipment age, technology assessment |
Working capital normalization ensures the business transfers with sufficient resources to operate effectively. Calculating business valuation on a cash-free, debt-free basis with normalized working capital creates cleaner transaction structures and reduces post-closing disputes.
Risk Assessment and Discount Rate Determination
The discount rate applied when calculating business valuation fundamentally reflects the risk an investor assumes in acquiring the business. Higher risk justifies higher required returns, which translate to lower valuations.
Building an Appropriate Discount Rate
The comprehensive valuation resources from NYU Stern provide datasets for estimating cost of equity, beta calculations, and industry-specific risk premiums. For private companies, building a discount rate typically starts with the risk-free rate, adds an equity risk premium, incorporates a size premium, and adjusts for company-specific risks.
Company-specific risk factors include:
- Customer concentration (single customer >20% of revenue)
- Key person dependency on owner or critical employees
- Geographic concentration limiting market diversification
- Technology or product obsolescence risk
- Regulatory or compliance vulnerabilities
- Competitive intensity and barriers to entry
Financial leverage also impacts valuation. Businesses carrying significant debt relative to cash flow present greater risk, requiring either higher discount rates or explicit modeling of the capital structure when valuing a firm through WACC-based methodologies.
For M&A transactions in the lower middle market, size premiums of 3-8% above standard equity risk premiums reflect the additional risk of smaller, less diversified businesses with limited access to capital markets.
Industry-Specific Valuation Considerations
Different industries demand tailored approaches when calculating business valuation. Software-as-a-Service businesses trade on revenue multiples and customer lifetime value metrics. Manufacturing companies emphasize EBITDA multiples adjusted for capital intensity. Professional services firms focus on recurring revenue and partner-level relationships.
Technology and Software Businesses
SaaS and technology companies often justify premium valuations based on recurring revenue, high gross margins, and scalability. Monthly Recurring Revenue (MRR), Annual Recurring Revenue (ARR), customer acquisition cost (CAC), and lifetime value (LTV) drive valuation more than traditional profitability metrics.
Growth rate significantly impacts technology valuations. A company growing 40% annually commands multiples several times higher than a business with 10% growth, even if current profitability is lower. Buyer due diligence focuses intensely on churn rates, expansion revenue, and unit economics.
Service-Based Businesses
Professional services, staffing agencies, and consulting firms present unique valuation challenges. Revenue concentration with individual clients or producers, the portability of client relationships, and the recurring nature of engagements all influence value. Calculating business valuation for service businesses often yields lower multiples than product or technology companies due to these challenges.
Transition planning becomes critical-demonstrating that client relationships extend beyond individual employees and that processes, systems, and brand value create sustainable competitive advantages justifies higher valuations.
Manufacturing and Distribution
Asset intensity, working capital requirements, and operating leverage characterize manufacturing and distribution businesses. Capital expenditure needs for equipment maintenance and replacement impact free cash flow generation. Supply chain relationships, production efficiency, and capacity utilization rates all factor into valuation analysis.
Location matters significantly for logistics and distribution businesses. Proximity to transportation infrastructure, labor markets, and customer concentrations creates geographic advantages that support premium valuations.
Due Diligence and Valuation Validation
Preliminary valuations calculated during initial deal exploration inevitably face scrutiny during formal due diligence. Quality of earnings (QoE) analysis, operational assessments, and legal review either validate or challenge initial valuation assumptions.
Financial Due Diligence
Third-party QoE reports examine revenue recognition policies, expense classification, working capital trends, and EBITDA adjustments. Discrepancies between seller-prepared financials and QoE findings often trigger valuation adjustments or deal renegotiation. The AICPA resources for valuation services provide professional standards that guide these assessments.
Revenue quality analysis investigates customer concentration, contract terms, renewal rates, and pricing power. Businesses with diversified revenue streams, long-term contracts, and demonstrated pricing discipline command premium valuations compared to those dependent on project-based or spot-market sales.
Operational and Strategic Assessment
Beyond financial analysis, calculating business valuation requires understanding operational capabilities, competitive positioning, and strategic fit. Management depth, technology infrastructure, intellectual property protection, and organizational capabilities all influence both valuation and transaction success probability.
For buyers using platforms that prioritize deal sourcing strategies focused on strategic fit, operational alignment often matters as much as financial metrics. A business that complements existing capabilities, provides geographic expansion, or fills product portfolio gaps may justify premium valuations based on synergy potential.
The confidential, secure nature of modern M&A platforms allows business owners to explore potential exits with qualified buyers without public market exposure or competitive intelligence risks-creating environments where honest valuation discussions can occur earlier in the process.
Tax and Legal Valuation Considerations
Transaction structure significantly impacts net proceeds to sellers and effective purchase price for buyers. Asset purchases, stock purchases, and various earn-out or seller financing arrangements create different tax consequences that influence valuation perspectives.
Tax-Affected Valuations
Asset sales typically generate higher tax liabilities for sellers due to depreciation recapture and ordinary income treatment of certain assets, while providing buyers with stepped-up basis and future tax benefits. Stock sales generally provide sellers with preferential capital gains treatment but offer buyers no basis step-up.
The IRS guidance on determining fair market value becomes relevant for estate planning, gift tax purposes, and ensuring defensible valuations for tax reporting. Professional appraisals following recognized standards protect against IRS challenges and provide documentation supporting reported values.
S-corporations, partnerships, and other pass-through entities present unique valuation considerations related to tax distributions, built-in gains, and historical tax elections that affect future after-tax cash flows.
Deal Structure Impact on Value
Earn-outs, seller notes, equity rollovers, and employment agreements all effectively adjust purchase price while managing risk allocation between parties. A $10 million cash-at-close deal differs fundamentally from a $7 million upfront payment with $3 million earn-out based on future performance.
When calculating business valuation for deal structuring purposes, present-value adjustments for deferred consideration, probability weighting of contingent payments, and risk discounts for seller financing components all influence effective economic value.
Technology Tools and Professional Resources
Modern valuation leverages specialized software, databases, and analytical tools that enhance accuracy and efficiency. While fundamental financial analysis remains essential, technology streamlines data gathering, scenario modeling, and sensitivity analysis.
Valuation Software and Databases
Comparable company databases provide transaction multiples, financial metrics, and deal terms for thousands of M&A transactions. These resources support market-based valuation approaches and validate income-based methodologies against actual market activity.
DCF modeling templates and specialized valuation software automate calculations, perform sensitivity analyses, and generate professional reports. Integration with financial statement data reduces manual data entry and calculation errors.
For M&A professionals working with private equity platforms and deal flow management systems, automated valuation screening helps prioritize opportunities that meet investment criteria before investing significant time in detailed analysis.
Virtual Data Rooms and Documentation
Secure document sharing through virtual data rooms facilitates efficient due diligence while maintaining confidentiality. For sellers after matching with qualified buyers, platforms offering complimentary secure data rooms remove cost barriers to professional transaction management.
The free virtual data room provided to matched sellers through certain M&A platforms demonstrates how technology reduces friction in the transaction process. Competitively priced VDR solutions for other market participants ensure all stakeholders can maintain professional standards without prohibitive costs. Buyers, sellers, and advisors not using match-making platforms can access competitive VDR pricing designed for lower middle-market transactions.
Organized documentation accelerates due diligence, reduces information asymmetries, and demonstrates seller professionalism-all factors that support valuation credibility and deal completion.
Negotiation Dynamics and Valuation Ranges
Calculating business valuation produces a range rather than a single definitive number. Professional valuations typically present a valuation range reflecting different methodologies, assumption sets, and perspectives on risk and growth potential.
Bridging Valuation Gaps
Buyers and sellers naturally approach valuation from different perspectives. Sellers focus on historical investment, peak performance periods, and growth potential. Buyers emphasize risks, required investments, and returns relative to alternative opportunities.
Successful negotiations acknowledge these different viewpoints while seeking common ground. Earnouts bridge gaps by linking future payments to performance milestones. Seller financing demonstrates seller confidence in business sustainability. Equity rollovers align seller interests with future success.
Strategies for valuation alignment:
- Focus discussion on underlying assumptions rather than final numbers
- Use multiple methodologies to establish credible ranges
- Identify and quantify areas of disagreement systematically
- Structure consideration to address specific concerns
- Emphasize strategic fit and synergy potential where applicable
Professional intermediaries bring objectivity, market knowledge, and negotiation experience that help parties reach mutually beneficial agreements. The SBA guidance on managing and valuing small businesses provides resources for business owners preparing for transactions.
Professional Standards and Ethical Considerations
Calculating business valuation carries professional responsibilities for accuracy, objectivity, and appropriate methodology application. Various professional organizations establish standards governing valuation practice.
The CFA Institute guidance on equity valuation outlines rigorous approaches appropriate for investment analysis and M&A contexts. The RICS standards for DCF valuation provide best-practice guidance for applying discounted cash flow methodologies professionally.
Independence and Objectivity
Valuation professionals must maintain independence from transaction outcomes when providing opinions for tax purposes, litigation support, or fairness opinions. Contingent fee arrangements that link compensation to valuation conclusions compromise objectivity and violate professional standards.
For M&A advisory work where the professional represents buyer or seller interests, transparency about the advocacy role and reliance on reasonable assumptions becomes critical for maintaining credibility and professional reputation.
Documentation supporting valuation conclusions, methodology selection rationale, and assumption development provides defensibility for tax authorities, litigation contexts, or professional peer review. Thorough work papers demonstrate professional diligence and support valuation credibility.
Calculating business valuation combines financial analysis, market knowledge, industry expertise, and professional judgment to establish credible value ranges that facilitate successful M&A transactions. Whether you're preparing to eventually sell your business or actively evaluating acquisition opportunities, understanding valuation fundamentals helps you engage in productive discussions grounded in market realities. Aligned IQ transforms the traditional M&A process by prioritizing strategic fit before delving deep into valuation negotiations-our proprietary matching platform connects buyers and sellers confidentially based on transaction priorities, deal size, and industry expertise, while our complimentary virtual data room for matched sellers ensures professional transaction management without cost barriers.
No responses yet