
Determining the accurate value of a startup company remains one of the most challenging aspects of mergers and acquisitions. Unlike established businesses with predictable cash flows and extensive financial histories, startups operate in environments characterized by rapid growth potential, limited historical data, and significant uncertainty. For business buyers, sellers, and M&A advisors navigating the lower middle market, understanding startup company valuation methodologies is essential for structuring fair deals that align with both strategic objectives and financial realities.
Understanding the Complexity of Startup Company Valuation
Startup company valuation differs fundamentally from traditional business valuation because early-stage companies lack the financial track records that make conventional methods straightforward. While mature businesses can rely on consistent revenue streams and established market positions, startups often operate at losses while investing heavily in growth, technology development, and market penetration.
The CFA Institute refresher on private-company valuation outlines three primary approaches: income-based methods (including discounted cash flow), market-based methods (using comparable transactions and multiples), and asset-based approaches. Each method requires careful adaptation when applied to startup environments.
The Revenue Stage Challenge
Revenue-generating startups present different valuation challenges than pre-revenue ventures. A typical scenario might involve a software-as-a-service company with eighteen months of operations, $500,000 in annual recurring revenue, and a clear path to profitability within thirty-six months. This company has demonstrable market traction but insufficient history for traditional earnings multiples.
In contrast, a pre-revenue biotechnology startup with promising intellectual property but years away from commercialization requires entirely different valuation logic. The gap between these scenarios explains why startup company valuation demands flexibility and multiple methodological perspectives.
Income-Based Valuation Methods for Startups
Discounted Cash Flow Analysis
The discounted cash flow (DCF) method projects future cash flows and discounts them to present value using a risk-adjusted discount rate. For startups, this approach encounters immediate obstacles: future cash flows are highly speculative, and determining an appropriate discount rate for unproven business models requires sophisticated judgment.
When applying DCF to startup company valuation, analysts typically:
- Develop multiple scenarios (optimistic, base case, pessimistic) to capture uncertainty
- Apply probability weightings to each scenario
- Use discount rates ranging from 25% to 50% depending on stage and sector
- Focus on terminal value calculations that assume eventual maturity
The KPMG valuation guidance emphasizes that professional judgment becomes critical when historical performance provides limited insight into future potential. For buyers exploring opportunities through deal sourcing platforms, understanding these DCF assumptions helps evaluate whether seller expectations align with defensible financial projections.
Revenue and EBITDA Multiples
Many practitioners prefer revenue multiples for startups that have achieved product-market fit but remain pre-profitable. Technology startups commonly trade at 2x to 10x annual recurring revenue, depending on growth rates, gross margins, customer retention metrics, and competitive positioning.
| Startup Characteristic | Typical Revenue Multiple Range | Key Value Drivers |
|---|---|---|
| High-growth SaaS (>100% YoY) | 8x – 12x ARR | Net revenue retention >120%, low churn |
| Moderate-growth SaaS (40-100% YoY) | 4x – 8x ARR | Strong unit economics, clear market position |
| Early-stage SaaS (<40% YoY) | 2x – 4x ARR | Proven model, path to profitability |
| E-commerce/Marketplace | 1x – 3x Revenue | Take rate, network effects, GMV growth |
For companies approaching profitability, EBITDA multiples become more relevant. However, startup company valuation using EBITDA requires adjustments for owner compensation, one-time expenses, and growth investments that temporarily suppress earnings.
Market-Based Valuation Approaches
Comparable Company Analysis
Identifying truly comparable companies challenges even experienced valuation professionals. Startups in emerging markets or with novel business models often lack direct peers. The analysis must consider:
- Industry and sector alignment – A fintech startup differs fundamentally from a healthcare technology company despite both being "tech" businesses
- Stage comparability – Comparing a seed-stage company to a Series B venture creates distortions
- Geographic factors – Market dynamics vary significantly across regions
- Business model nuances – Subscription versus transactional revenue models command different multiples
The Stanford Graduate School of Business analysis of unicorn valuations demonstrates how outlier companies can skew perceptions of typical startup values. Most lower middle-market startups operate far from unicorn territory, requiring more grounded comparable selection.
Recent Transaction Data
Precedent transaction analysis examines actual deals involving similar companies. This method provides real-world validation of valuation assumptions, though transaction data for private companies remains limited and often incomplete.
When evaluating transaction comparables for startup company valuation purposes, consider:
- Transaction structure (asset vs. stock purchase)
- Earnout provisions and contingent consideration
- Strategic versus financial buyer premiums
- Market conditions at transaction date
- Synergy expectations unique to specific buyers
The 409A Valuation Requirement
Startups issuing stock options to employees must obtain periodic 409A valuations to comply with federal tax regulations. The U.S. Treasury regulations governing Section 409A require that stock options be granted at fair market value to avoid adverse tax consequences for employees.
Safe Harbor Methods
The IRS provides safe harbor protection for 409A valuations performed by independent appraisers using reasonable methodologies. These valuations typically employ a combination of:
- Option Pricing Model (OPM) – Treats equity classes as call options on enterprise value
- Probability-Weighted Expected Return Method (PWERM) – Assigns probabilities to different liquidity scenarios
- Hybrid approaches – Combines OPM and PWERM for different time horizons
The IRS guidance on fair market value determination emphasizes that valuations must reflect current conditions and realistic assumptions. For business owners preparing their companies for eventual sale, maintaining compliant 409A valuations creates a documented valuation history that can facilitate buyer due diligence.
Strategic Considerations Beyond Financial Metrics
While quantitative methods provide valuation frameworks, startup company valuation ultimately depends on strategic factors that financial models struggle to capture fully.
Intellectual Property and Technology Assets
Patents, proprietary algorithms, and unique datasets can represent the majority of a startup's value, yet traditional financial statements fail to reflect these assets adequately. Buyers must assess:
- Defensibility of intellectual property positions
- Technical moat versus competitors
- Dependency on key personnel
- Technology scalability and architecture quality
Team Quality and Management Depth
Experienced M&A professionals recognize that early-stage company value resides heavily in founder expertise and team capabilities. A scenario involving a fintech startup might reveal that the founding team's previous successful exits and domain expertise justify premium valuations despite limited current revenues.
Market Position and Competitive Dynamics
Startups occupying defensible market niches or demonstrating winner-take-all network effects command higher valuations than commoditized offerings. Strategic buyers often pay significant premiums for startups that fill product gaps or accelerate market entry strategies.
Valuation Adjustments for Startup-Specific Factors
Illiquidity Discount
Private company ownership lacks the liquidity of public markets, warranting discounts typically ranging from 20% to 40% depending on expected holding periods and exit clarity. Startup company valuation requires careful consideration of when and how investors might achieve liquidity.
Control Premium
Buyers acquiring majority stakes typically pay premiums of 20% to 35% above minority interest values, reflecting the ability to direct strategy, access cash flows, and determine exit timing. In lower middle-market transactions, control considerations significantly impact final valuations.
Key Person Dependency
Many startups rely heavily on founders or specific technical leaders. If key individuals plan to depart post-transaction, valuation discounts may reach 30% to 50% depending on business complexity and knowledge transfer feasibility.
Negotiating Valuation in the Deal Process
Earnouts and Contingent Consideration
When buyers and sellers disagree on startup company valuation, earnout provisions bridge gaps by tying portions of purchase price to future performance. Typical earnout structures include:
| Earnout Type | Typical Duration | Performance Metrics | Buyer Considerations |
|---|---|---|---|
| Revenue-based | 12-36 months | Top-line growth targets | Easier to verify, less manipulation risk |
| EBITDA-based | 24-36 months | Profitability milestones | Accounting discretion concerns |
| Milestone-based | 12-48 months | Product launches, customer wins | Clear binary outcomes |
| Hybrid | 24-36 months | Multiple metrics | Balanced risk allocation |
Business owners considering earnout proposals should carefully evaluate the feasibility of targets under new ownership and ensure they retain sufficient operational control to influence outcomes.
Seller Financing and Rollover Equity
Sellers confident in their startup's trajectory may accept partial payment through seller notes or retained equity stakes. These structures allow higher headline valuations while aligning incentives around post-close performance. For buyers utilizing acquisition strategies that conserve capital, seller financing can enable transactions that cash-only offers cannot support.
Leveraging Technology in the Valuation Process
Modern business valuation software streamlines data collection, comparable company analysis, and scenario modeling. These platforms help standardize methodologies while allowing customization for startup-specific factors.
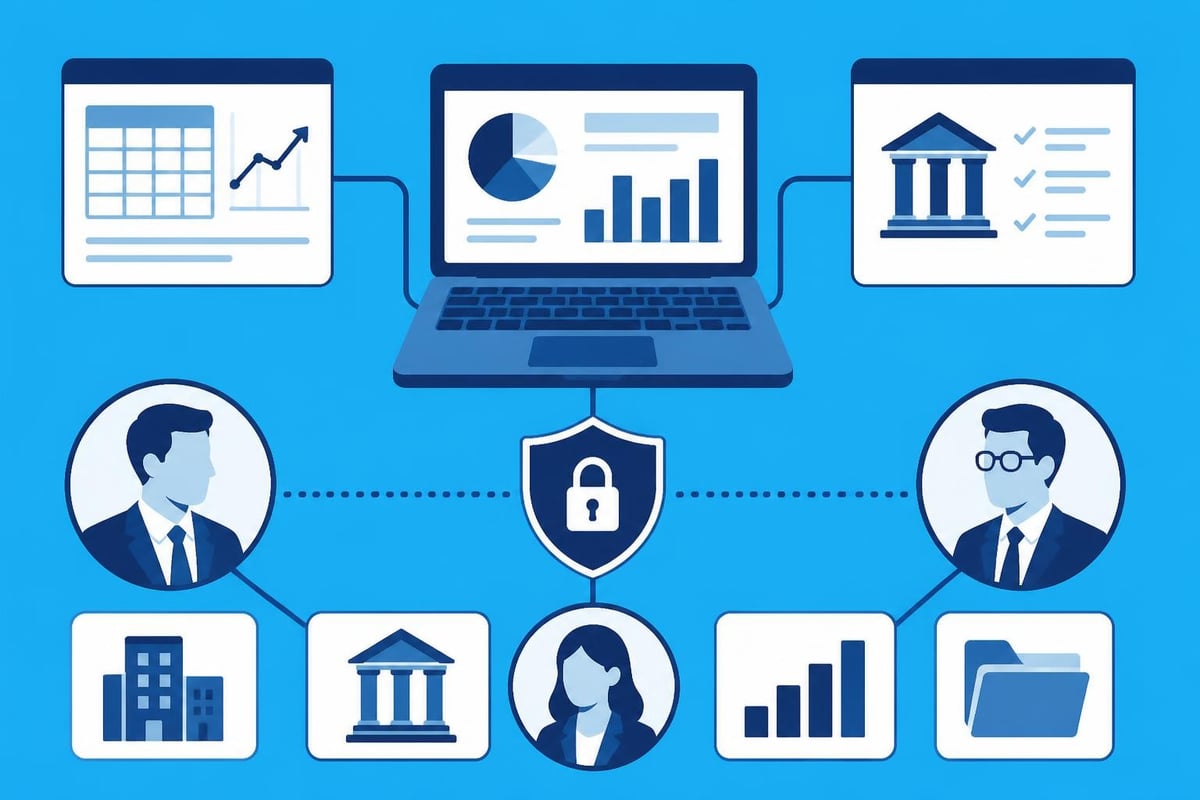
For business sellers preparing for eventual transactions, platforms prioritizing strategic fit before diving into detailed valuation discussions reduce wasted effort on mismatched opportunities. Understanding how potential buyers value specific business attributes allows sellers to highlight strengths that command premium multiples.
Sector-Specific Valuation Nuances
Technology and Software Startups
Software businesses benefit from high gross margins, recurring revenue models, and scalability, justifying premium valuations. Key metrics include:
- Customer acquisition cost (CAC) to lifetime value (LTV) ratios
- Monthly recurring revenue (MRR) growth rates
- Net revenue retention percentages
- Gross margin sustainability
Healthcare and Biotech Ventures
These startups often operate pre-revenue while pursuing regulatory approvals. Valuation depends on clinical trial results, intellectual property strength, market size for target indications, and probability-adjusted revenue forecasts extending decades into the future.
Consumer and E-Commerce Companies
Direct-to-consumer brands and marketplace businesses emphasize unit economics, customer cohort behavior, and brand equity. Valuation multiples correlate strongly with repeat purchase rates and customer lifetime values.
Professional Services and Agencies
Service businesses with lower gross margins and higher personnel dependency typically command lower multiples than technology startups. Startup company valuation in these sectors focuses on contract backlog, client concentration, and team retention probabilities.
The Role of Third-Party Valuation Experts
Complex transactions often warrant independent valuation opinions from qualified business appraisers holding credentials such as ASA (Accredited Senior Appraiser) or CVA (Certified Valuation Analyst). These professionals provide:
- Objective analysis free from buyer or seller bias
- Defensible methodologies that withstand scrutiny from lenders, investors, and tax authorities
- Documentation supporting tax compliance and financial reporting
- Negotiation support helping parties understand valuation drivers and trade-offs
For transactions involving SBA financing, earnouts, or significant tax implications, professional valuation reports often prove essential.
Preparing Startups for Optimal Valuations
Business owners planning eventual exits can take specific actions to maximize startup company valuation:
- Establish clean financial records – Implement proper accounting systems and clear documentation of revenue recognition policies
- Build recurring revenue – Transition from project-based to subscription or retainer models where feasible
- Reduce customer concentration – Diversify customer base to minimize key account dependency
- Protect intellectual property – File patents, register trademarks, and document proprietary processes
- Develop management depth – Build teams capable of operating without constant founder involvement
- Document systems and processes – Create transferable knowledge that survives ownership transitions
These improvements both increase actual business value and enhance buyer confidence, often justifying premium multiples.
Connecting Buyers and Sellers Strategically
Traditional M&A processes often begin with valuation discussions before establishing strategic alignment, leading to wasted time when fundamental incompatibilities emerge. Alternative approaches prioritize fit assessment, allowing valuation negotiations to occur only after mutual interest is confirmed.
For business owners seeking eventual exits, platforms emphasizing confidential exploration of strategic matches reduce the risk of premature disclosure while improving the quality of potential buyers. This approach acknowledges that startup company valuation depends heavily on strategic considerations unique to each buyer-seller pairing.
Similarly, business buyers benefit from showcasing their acquisition criteria, industry expertise, and value-creation capabilities before diving into specific opportunities. This positioning helps attract sellers whose businesses align with buyer strengths, facilitating more efficient valuation discussions based on genuine synergy potential.
Data Room Requirements and Valuation Support
Once preliminary valuation ranges are established and serious negotiations begin, secure document sharing becomes critical. Virtual data rooms enable buyers to conduct thorough due diligence while sellers maintain control over sensitive information access.
Competitively priced solutions like those available through Aligned IQ VDR pricing provide lower middle-market participants with enterprise-grade security without prohibitive costs. For sellers who have identified matches through strategic alignment processes, complimentary data room access removes friction from the diligence phase.
Comprehensive data rooms supporting startup company valuation should include:
- Historical financial statements and projections
- Customer contracts and retention metrics
- Intellectual property documentation
- Employment agreements and organizational charts
- Technology architecture and security audits
- Cap tables and previous financing documentation
Common Valuation Pitfalls to Avoid
Overreliance on Single Methods
Using only one valuation approach creates vulnerability to methodological limitations. Professional practice recommends triangulating across multiple methods and reconciling differences through careful analysis of each approach's applicability to specific circumstances.
Ignoring Market Conditions
Valuation multiples fluctuate with market cycles, interest rate environments, and sector-specific trends. Startup company valuation based on peak-market comparables may prove unrealistic during subsequent downturns.
Failure to Adjust for Normalization
Financial statements must be adjusted for:
- Owner compensation exceeding market rates
- One-time expenses unlikely to recur
- Personal expenses run through the business
- Deferred maintenance requiring future investment
These normalizing adjustments often significantly impact calculated values.
Neglecting Integration Costs
Buyers must account for transaction costs, system integration expenses, and potential revenue disruption during ownership transitions. These factors reduce net present value despite strong standalone business performance.
Understanding startup company valuation requires combining technical financial analysis with strategic assessment of unique business attributes, market positions, and growth potential. Whether you're a business owner planning an eventual exit, a buyer seeking strategic acquisitions, or an advisor facilitating transactions, mastering these methodologies creates foundations for successful deal-making. Aligned IQ transforms the traditional M&A process by prioritizing strategic fit before deep valuation discussions, helping buyers and sellers find ideal counterparties based on transaction priorities, deal size, and industry expertise. Take a tour to discover how our confidential matching process and complimentary virtual data room for matched sellers can streamline your path to successful transactions.
No responses yet