

Business owners contemplating exit strategies or strategic acquisitions need credible, defensible valuations to support their decisions. Business valuation firms provide the specialized expertise required to determine fair market value, assess deal structures, and support negotiations with objective financial analysis. Whether you're preparing for a sale, exploring acquisition opportunities, or requiring valuations for tax or compliance purposes, understanding how these firms operate and what they deliver becomes essential for successful transactions.
What Business Valuation Firms Do and Why They Matter
Business valuation firms specialize in determining the economic value of a company or business interest. These professional service providers employ certified appraisers who apply rigorous methodologies to assess what a business is worth under various scenarios and purposes.
The role of business valuation firms extends far beyond simply assigning a number to a company. They provide critical analysis that informs transaction decisions, supports litigation, satisfies regulatory requirements, and helps owners understand the true worth of their enterprise. A certified business appraiser brings professional credentials and adherence to established standards that ensure credibility and defensibility.
Core Services Offered
Most business valuation firms provide a comprehensive range of services tailored to different needs:
- Transaction support for mergers, acquisitions, and divestitures
- Tax compliance valuations for estate planning, gift tax, and ESOPs
- Financial reporting valuations under ASC 805, 820, and 350
- Litigation support for shareholder disputes, divorce proceedings, and damage calculations
- Strategic planning valuations for internal decision-making
- Fairness opinions for board-level transaction approval
The depth and formality of the engagement vary based on purpose. A full appraisal report suitable for IRS scrutiny differs substantially from a calculation of value for preliminary transaction discussions.
Valuation Methodologies and Approaches
Professional business valuation firms rely on three fundamental approaches recognized by International Valuation Standards and other authoritative bodies. Each approach offers different perspectives on value, and skilled appraisers typically employ multiple methods to triangulate a defensible conclusion.
Income Approach
The income approach determines value based on the present value of future economic benefits. This forward-looking methodology appeals particularly to buyers focused on return on investment.
Discounted Cash Flow (DCF) represents the most sophisticated income method. Appraisers project future cash flows over a discrete period, then calculate a terminal value for periods beyond the projection. These cash flows are discounted to present value using a rate that reflects the risk profile of the investment. The Pepperdine Graziadio Private Capital Markets Report provides valuable market data for establishing appropriate discount rates.
Capitalization of Earnings offers a simpler alternative when a company demonstrates stable, predictable earnings. A single period's normalized earnings is divided by a capitalization rate that reflects growth expectations and risk. This method works well for mature businesses with consistent performance.
Market Approach
The market approach derives value by comparing the subject company to similar businesses that have sold or public companies in comparable industries. This approach grounds valuations in actual transaction data rather than theoretical projections.
Guideline Public Company Method analyzes publicly traded companies with similar characteristics. Valuation multiples (such as price-to-earnings or enterprise value-to-EBITDA) are extracted from public markets, then adjusted for differences in size, liquidity, and risk before applying to the subject company.
Guideline Transaction Method examines actual sales of comparable private companies. This method provides particularly relevant benchmarks for M&A transactions, though data availability can be challenging. Understanding valuing private companies requires recognizing the adjustments needed when comparing private businesses to public market data.
| Method | Data Source | Best For | Limitations |
|---|---|---|---|
| Guideline Public Company | Public market data | Companies in industries with public comparables | Requires size and liquidity adjustments |
| Guideline Transaction | Private transaction databases | M&A scenarios | Limited data availability |
| Prior Transactions | Subject company's own history | Establishing floor values | May not reflect current conditions |
Asset Approach
The asset-based approach calculates value by adjusting the company's balance sheet to fair market value. This method proves most relevant for holding companies, asset-intensive businesses, or situations where the company's value derives primarily from its tangible assets rather than earnings power.
Business valuation firms typically employ this approach as a floor value rather than the primary indicator for operating companies with significant going-concern value. However, it remains essential for certain industries and provides a critical check against other methodologies.
Selecting the Right Business Valuation Firm
Not all business valuation firms offer the same expertise, credentials, or industry focus. Choosing the right firm directly impacts the credibility of your valuation and its utility for your intended purpose.
Professional Credentials Matter
The most qualified valuators hold certifications from recognized professional organizations. The American Society of Appraisers awards the Accredited Senior Appraiser (ASA) designation, while other respected credentials include the Accredited in Business Valuation (ABV) from the AICPA and Certified Valuation Analyst (CVA) from the National Association of Certified Valuators and Analysts.
These credentials require rigorous examination, demonstrated experience, and ongoing continuing education. They signal competence and adherence to professional standards that enhance defensibility when valuations face scrutiny.
Industry Expertise and Transaction Experience
Business valuation firms often specialize in particular industries or transaction types. A firm with deep healthcare experience brings insights about regulatory trends, reimbursement dynamics, and industry-specific risks that generalists might miss.
Similarly, firms experienced in M&A transactions understand buyer perspectives, deal structures, and negotiation dynamics differently than firms focused primarily on tax compliance work. When preparing for a potential sale, engaging a firm familiar with how lower middle-market PE firms evaluate opportunities can provide strategic advantages.
Independence and Objectivity
The credibility of a valuation depends heavily on the appraiser's independence. Business valuation firms must avoid conflicts of interest that could bias their conclusions. The IRS Business Valuation Guidelines specifically address independence requirements for appraisers whose work supports tax positions.
For M&A transactions, some buyers and sellers prefer separate valuation firms to avoid any perception of bias. This approach ensures each party receives objective analysis supporting their decision-making.
The Valuation Process and Timeline
Understanding how business valuation firms conduct their work helps set appropriate expectations for timeline and information requirements.
Initial Engagement and Scope Definition
The process begins with defining the scope of work. Business valuation firms need clarity on:
- Purpose of the valuation (transaction support, tax compliance, litigation, etc.)
- Standard of value (fair market value, fair value, investment value)
- Valuation date and any specific assumptions or limiting conditions
- Report type (calculation, limited appraisal, or comprehensive appraisal report)
- Timeline requirements and budget parameters
A typical scenario might involve a business owner exploring exit options who engages a valuation firm for a preliminary calculation of value. This limited-scope engagement provides a defensible range of values to inform initial discussions without the cost and time of a full appraisal report.
Information Gathering and Due Diligence
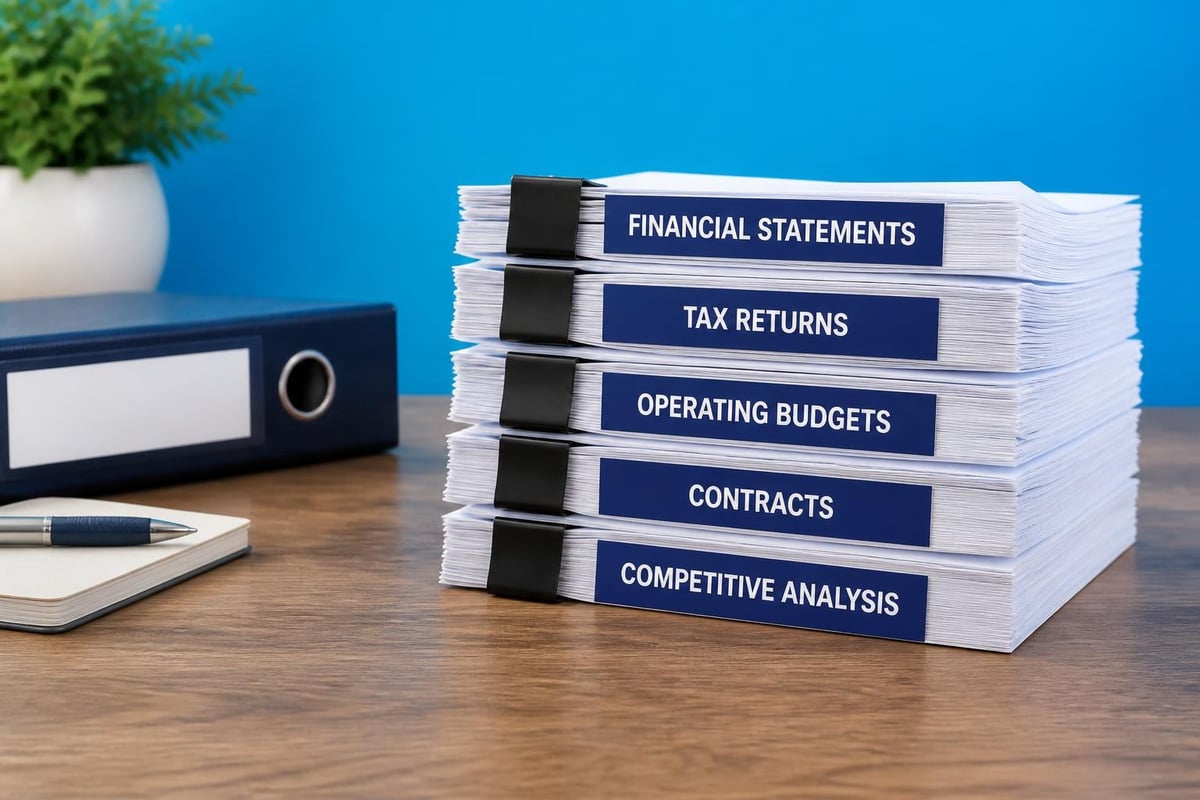
Business valuation firms require substantial financial and operational information. The typical request list includes:
- Historical financial statements (typically three to five years)
- Tax returns for corresponding periods
- Detailed operating budgets and forecasts
- Customer concentration analysis
- Organizational charts and management bios
- Copies of material contracts and leases
- Details of any pending litigation or contingent liabilities
- Industry research and competitive positioning
The quality and completeness of information directly impact both timeline and valuation quality. Companies with clean financials, well-documented operations, and organized records expedite the process significantly.
Analysis and Report Preparation
The core analytical work involves applying selected methodologies, adjusting for company-specific factors, and reconciling conclusions from different approaches. Business valuation firms invest significant professional judgment in:
- Normalizing earnings by removing non-recurring items and owner discretionary expenses
- Developing discount rates that reflect company-specific risk factors
- Selecting comparable companies and justifying adjustments
- Applying discounts for lack of marketability or minority interests
- Reconciling multiple approaches to a final value conclusion
Timeline varies based on engagement scope, company complexity, and information availability. A calculation of value might require two to three weeks, while comprehensive appraisal reports often span four to six weeks or longer for complex situations.
Valuation Report Types and Their Applications
Business valuation firms deliver different report formats depending on the engagement's purpose and requirements.
| Report Type | Characteristics | Typical Uses | Relative Cost |
|---|---|---|---|
| Calculation of Value | Limited scope; restricted assumptions; minimal report | Preliminary M&A discussions; internal planning | $ |
| Limited Appraisal Report | Moderate detail; abbreviated assumptions disclosure | Some transactions; certain tax filings | $$ |
| Comprehensive Appraisal Report | Full detail; complete methodology disclosure | IRS scrutiny; litigation; significant transactions | $$$ |
The decision about report type should align with the anticipated level of scrutiny and the consequences of the valuation. Tax matters likely to face IRS examination warrant comprehensive reports, while preliminary acquisition screening may require only calculations.
Navigating Tax and Regulatory Considerations
Business valuation firms must navigate complex regulatory frameworks that govern valuation practice, particularly for tax-related engagements.
IRS Requirements and Standards
The Internal Revenue Service maintains specific guidelines for acceptable valuation reports and qualified appraisers. These requirements have become increasingly stringent following legislative changes and enforcement focus on aggressive valuation positions.
Appraisers supporting tax positions must demonstrate appropriate qualifications, follow recognized methodologies, and provide sufficient detail to allow independent review. The consequences of inadequate valuations extend beyond potential tax adjustments to include penalties for substantial or gross valuation misstatements.
International Valuation Standards
Companies involved in cross-border transactions or subject to international financial reporting requirements must consider global valuation standards. The RICS Valuation standards provide guidance for internationally recognized valuation practice, while Deloitte’s Fair Valuation Survey offers insights into how major advisory firms approach complex valuations across jurisdictions.
These standards influence methodology selection, disclosure requirements, and the professional qualifications expected of valuators. Business valuation firms serving multinational clients or handling complex financial reporting valuations must maintain expertise in these evolving frameworks.
How Valuations Inform M&A Strategy
For business owners considering exit strategies and potential acquirers evaluating opportunities, business valuation firms provide essential intelligence that shapes transaction approaches and negotiation positions.
Establishing Realistic Expectations
One of the most valuable contributions business valuation firms make is anchoring seller expectations to market reality. Many owners overestimate their company's value based on emotional attachment, historical investment, or anecdotal information about seemingly comparable transactions.
A professional valuation grounds discussions in defensible analysis. Understanding the enterprise value of a firm and how different buyers might perceive value creation opportunities helps sellers identify the right counterparties and structure deals appropriately.
Supporting Deal Structuring and Negotiations
Valuations inform more than just price discussions. They highlight value drivers, risk factors, and areas requiring due diligence focus. Business valuation firms often identify:
- Working capital requirements that affect cash-free, debt-free calculations
- Earnout opportunities where future performance can bridge valuation gaps
- Asset allocation for tax-efficient transaction structures
- Quality of earnings issues that warrant price adjustments or representations
This analysis proves particularly valuable when exploring strategic fit through platforms that prioritize alignment before extensive due diligence commitments.
Quality of Earnings vs. Business Valuation
While business valuation firms determine what a company is worth, quality of earnings (QoE) studies examine whether reported earnings accurately reflect sustainable performance. Both analyses serve distinct but complementary purposes in M&A transactions.
A typical scenario might involve a seller obtaining a business valuation to establish asking price expectations, while a buyer commissions a QoE study during due diligence to verify that EBITDA justifies the agreed-upon valuation. Understanding these distinct roles helps parties structure appropriate professional engagements at each transaction stage.
Emerging Trends Affecting Business Valuations
The valuation profession continues evolving in response to market dynamics, technological advancement, and regulatory developments.
Technology and Data Analytics
Business valuation firms increasingly leverage sophisticated analytics, machine learning, and expanded databases to enhance their analysis. Business valuation software enables more efficient comparable company analysis, sensitivity testing, and report generation.
However, technology complements rather than replaces professional judgment. The most critical valuation decisions-selecting appropriate methodologies, developing reasonable assumptions, and exercising discretion about company-specific factors-remain fundamentally professional services requiring human expertise.
Market Volatility and Economic Uncertainty
Economic conditions in 2026 present unique challenges for business valuation firms. Inflation concerns, interest rate dynamics, and market volatility complicate traditional approaches to determining discount rates and projecting cash flows.
Appraisers must carefully consider how macroeconomic factors affect specific industries and companies. A small business valuation requires particular sensitivity to how economic conditions impact access to capital, customer behavior, and competitive dynamics at the lower end of the market.
ESG Considerations
Environmental, social, and governance factors increasingly influence business valuations as investors recognize their impact on long-term value creation and risk. Business valuation firms now incorporate ESG analysis when assessing:
- Regulatory compliance risks and potential remediation costs
- Customer and employee attraction advantages for companies with strong ESG profiles
- Access to capital and favorable financing terms
- Long-term competitive positioning and industry dynamics
These considerations particularly affect certain industries but increasingly extend to companies of all sizes as stakeholder expectations evolve.
Cost Considerations and Budgeting
Understanding the investment required for professional valuation services helps companies budget appropriately and select engagement types matching their needs.
Factors Affecting Valuation Costs
Business valuation firms typically price engagements based on several variables:
- Complexity of business operations (multiple locations, business segments, revenue streams)
- Quality and organization of financial information provided
- Report type and detail level required
- Purpose and anticipated scrutiny level
- Timeline urgency and competing priorities
- Industry specialization requirements
A straightforward, single-location service company with clean financials might require substantially less professional time than a multi-division manufacturer with complex transfer pricing, international operations, and aggressive accounting policies.
Comparing Value vs. Cost
While comprehensive appraisal reports from top-tier business valuation firms represent significant investments, they often prove economical relative to transaction values or tax consequences. An inadequate valuation supporting an estate tax return might save professional fees initially but result in substantial penalties, interest, and tax adjustments later.
For M&A purposes, accurate valuations help avoid overpaying for acquisitions or underpricing businesses for sale. Even modest valuation improvements typically dwarf the cost of professional services on transactions of any meaningful size.
Coordinating Valuations with Other Professional Advisors
Business valuation firms function most effectively when coordinated with other advisors supporting transaction objectives.
Integration with M&A Advisors and Investment Bankers
Investment bankers and M&A advisors rely on business valuation firms to provide objective analysis supporting their marketing and negotiation efforts. However, these roles differ fundamentally.
Advisors advocate for their clients to achieve optimal transaction outcomes. They leverage valuations as negotiating tools but ultimately focus on market conditions, buyer motivations, and competitive dynamics that influence actual transaction values. Business valuation firms provide independent analysis of fair market value without advocacy roles.
This distinction matters when sellers explore strategic alternatives. An objective valuation informs realistic expectations, while M&A advisors work to achieve premium outcomes through effective positioning and competitive processes. Platforms prioritizing strategic fit before extensive process costs help ensure the right counterparties engage seriously, making professional valuations more impactful.
Coordination with Legal and Tax Advisors
Attorneys structure transactions to achieve legal and tax objectives while protecting clients' interests. Tax advisors optimize tax positions within allowable frameworks. Business valuation firms provide analysis supporting these goals but must maintain independence from advocacy positions.
Effective coordination requires clear communication about engagement purposes, reporting requirements, and how valuation conclusions integrate with broader transaction or tax strategies. The timing of valuation work relative to transaction milestones or tax filing deadlines requires careful planning across the professional team.
Special Valuation Situations
Certain circumstances require specialized expertise beyond standard business valuation approaches.
Startups and Early-Stage Companies
Business valuation firms face particular challenges valuing companies with limited operating history, negative earnings, or unproven business models. Traditional income approaches struggle when reliable cash flow projections prove elusive, while market approaches require identifying truly comparable ventures.
Valuators often employ venture capital methods, real option frameworks, or probabilistic scenarios reflecting the unique risk-return profiles of early-stage businesses. These specialized approaches require different expertise than mature company valuations.
Distressed Companies and Restructuring Situations
Valuing businesses facing financial distress, bankruptcy proceedings, or restructuring requires analyzing multiple value scenarios-going concern value, orderly liquidation value, forced liquidation value-and understanding the legal frameworks governing creditor priorities and stakeholder recoveries.
Business valuation firms serving restructuring situations must coordinate closely with bankruptcy counsel, turnaround advisors, and courts to ensure their analysis addresses the specific legal standards and decision contexts at issue.
Complex Capital Structures
Companies with multiple classes of equity, convertible securities, warrants, or option pools require sophisticated valuation techniques to allocate enterprise value among different security classes. The option-pricing method and probability-weighted expected return method help address these complexities.
These situations frequently arise with private equity investments, management buyouts, and companies preparing for liquidity events. Business valuation firms must carefully model waterfall provisions, participation rights, and other features affecting value distribution.
Business valuation firms provide the professional expertise and objective analysis essential for informed M&A decisions, tax compliance, and strategic planning. Understanding their methodologies, selecting qualified practitioners, and coordinating their work with your broader objectives ensures you receive maximum value from these critical professional services. When you're ready to explore strategic transactions with confidence in your company's worth and strategic fit with potential counterparties, Aligned IQ offers a proprietary platform where buyers and sellers meet privately to explore opportunities based on transaction priorities, deal size, and industry expertise-with complimentary access to competitively-priced virtual data room services for matched parties. Take a tour to discover how prioritizing strategic alignment transforms the M&A process.
No responses yet